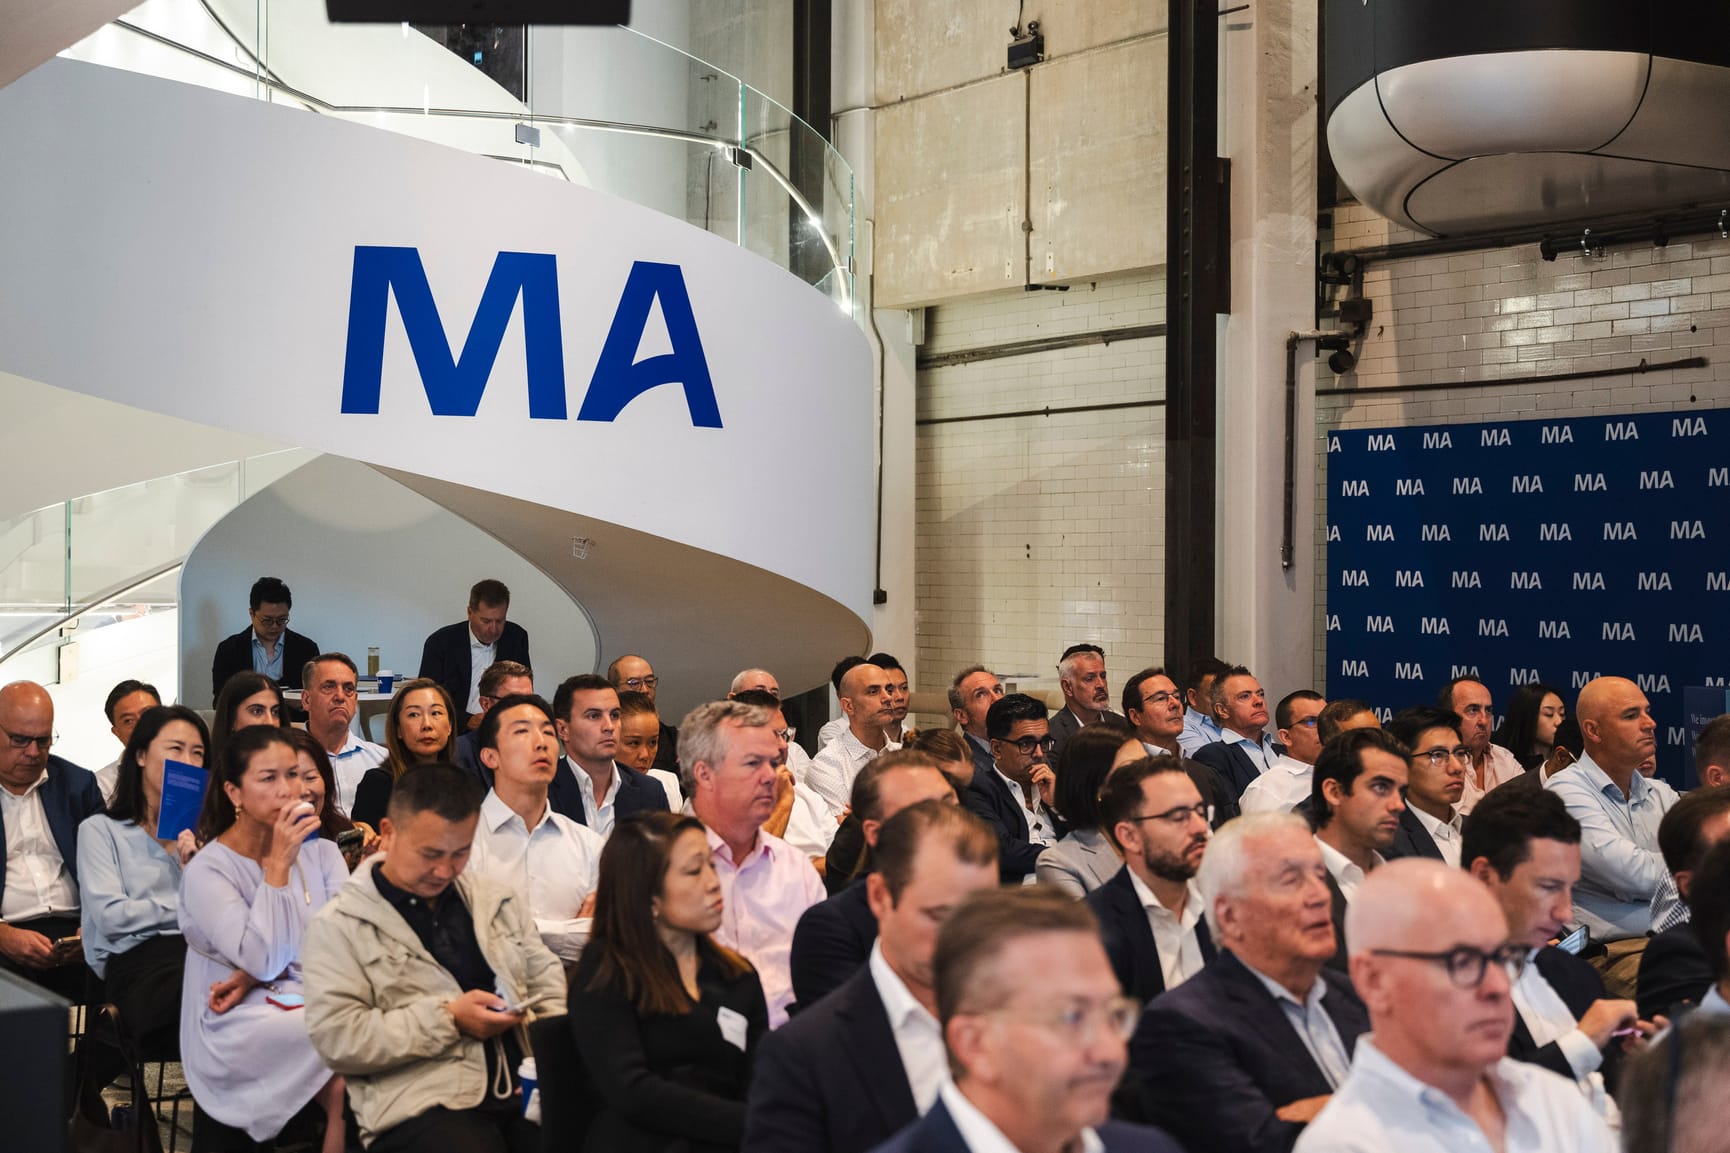
At our third annual MA Alternatives Summit our in-house experts were joined by leading industry voices to explore the latest trends and new frontiers shaping the future of alternative investments.
See below for highlights and key takeaways from each session.
An evidenced-based look at the structural forces shaping alternative investments
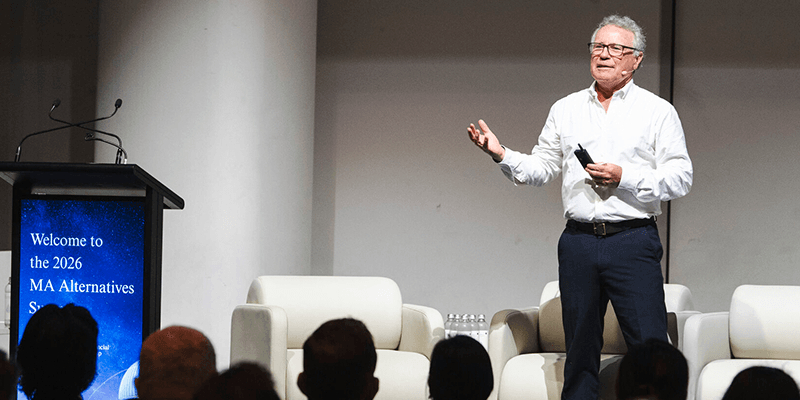
We kicked off the first of the Summit’s five sessions with Tim Farrelly, Co-Chief Investment Officer and Head of Asset Allocation at Delta Portfolios.
Tim set the scene with a data-driven macro perspective, drawing on deep historical analysis to examine how a range of alternative strategies have performed across market cycles, and what that means for investors today.
Key takeaways from Tim’s session included:
- Alternatives should not be viewed simply as a reaction to recent market volatility. Instead, they need to be considered against a backdrop of more realistic forward-looking return expectations for public markets
- Not all alternatives are created equal. Outcomes vary significantly across asset classes, structures and managers – with entry price and manager selection far more important than a generic allocation to “alts”
- Focus on data and evidence over short-term noise. Understanding what has historically driven returns, and whether those drivers remain intact, is critical to setting sound investment assumptions.
How institutional capital is allocating to private markets
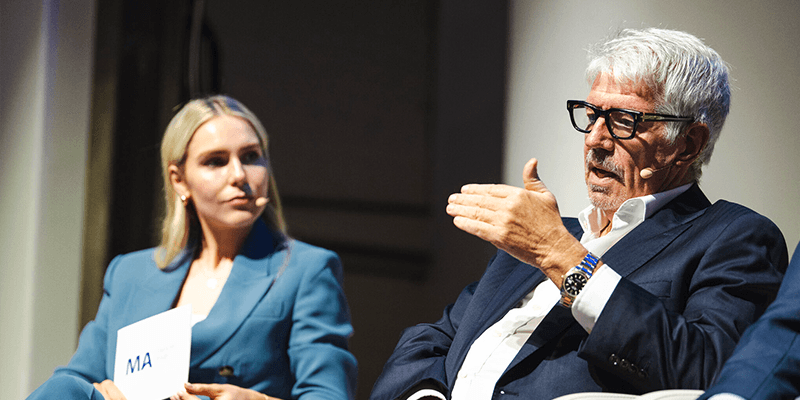
In a panel moderated by Executive Director Adam Trimboli, we heard from leading APAC institutional investors: Stephen Darke, CEO of Navigator Global Investments Limited and Felicity Walsh, Managing Director, ANZ, Head of Institutional Business, APAC (ex-Japan) at Franklin Templeton.
Stephen and Felicity’s discussion offered a practical lens on how institutional capital is being deployed across private markets today, with several clear themes emerging:
- Private markets are no longer a satellite allocation – they are increasingly viewed as core to portfolio construction
- Manager selection has never been more critical. The dispersion between top and bottom quartile managers continues to widen, with track record across cycles, scalability, AUM and operational strength all key considerations
- Investors are becoming more selective and more global, diversifying beyond the US and Europe in search of new opportunities.
This was a timely perspective on how sophisticated capital is navigating an evolving private markets landscape.
Uncovering the next opportunity in Australian real estate
Turning to one of the most enduring and closely watched asset classes – Australian real estate – our next session brought together deep experience across cycles and sectors.
Moderated by Distribution Director Madelaine Promnitz, the panel featured Anthony Kingsley from Proprium Capital Partners alongside our Joint CEO Julian Biggins and Director – Retail Greg Miles, who shared their perspectives on current conditions, how capital is being positioned today, and where they see the most compelling opportunities.
Distilling their informative discussion into a few key takeaways:
- Australia continues to benefit from strong structural tailwinds including population growth, constrained land supply, resilient consumer demand and a relatively stable political environment, underpinning long-term real estate fundamentals
- Active management is critical. Across sectors – from retail and residential to pubs, marinas and alternative living – driving tenant demand, executing capex effectively and enhancing operational performance are key to outcomes
- This is not a market for passive exposure or reliance on cap rate compression. Success requires pricing discipline, specialist expertise, scalable platforms and repeatable value creation
- At this stage of the cycle, fundamentals and discipline matter more than ever. Dispersion across sub-sectors is significant, with quality assets in the right locations, and the right management, increasingly differentiating performance.
Avoiding the losers in crowded private credit markets
In 2026 and beyond, the defining question for private credit investors is no longer “Do I have exposure?” but “What do I own – and how resilient is it?”
In a powerhouse panel discussion moderated by our Head of Global Credit Solutions Frank Danieli, Mark Glengarry from Blackstone, Bob Sahota of Revolution Asset Management and Byron Beath from Oaktree unpacked the importance of credit discipline in an increasingly crowded and complex market.
Key themes from their discussion included:
- Private credit remains a highly compelling asset class if done right, but there is a wide spectrum of managers and strategies. Not every manager or every strategy makes sense
- If you haven’t been disciplined, it could be too late. The best managers have always had a clear focus on ‘avoiding losers’, rather than stretching for yield to deploy capital
- The strongest managers differentiate through proprietary origination, deep sector expertise across cycles, and rigorous underwriting standards
- The ‘rising tide lifts all ships’ era of private credit is over. Investors need to look beyond headline yields and understand what sits “under the hood”, including borrower resilience, structural protections and covenants, manager alignment, and the realism of underwriting assumptions
- Manager selection and transparency are critical. Dispersion is increasing, and not all capital is being deployed with the same level of discipline.
A clear takeaway: in today’s market, understanding risk is just as important as generating returns.
Investing in the AI era
We closed the MA Alternatives Summit with a forward-looking session on one of the most transformative forces shaping markets – AI.
The panel brought together perspectives from across the investment spectrum: Brian Hartzer from Quantium, Michael Kron from Antler and Rami Mukhtar from Potentia Capital to explore how AI is reshaping both company formation and the investment case for existing businesses.
The group explained:
- The AI opportunity spans both disruptors and incumbents. AI-native companies are emerging rapidly, building faster, leaner and more scalable models from day one. At the same time, incumbents that successfully embed AI can enhance margins, improve customer outcomes and strengthen competitive positioning
- For investors, opportunity exists at both ends: backing AI-first businesses early, as well as identifying established companies where AI can unlock meaningful operational transformation
- Underwriting AI requires a new lens on risk and defensibility. Key considerations include speed of adoption, access to proprietary data, the durability of competitive advantage, and whether perceived “moats” are truly sustainable in a fast-evolving landscape.
AI is not a fad or theme on the horizon. It is already central to how the next generation of market leaders will be built.
In this short video we revisit key moments from the 2026 MA Alternatives Summit.
The takeaway was clear: alternatives – or more accurately, private assets – are no longer niche. They are becoming a core component of how sophisticated capital is allocated globally.